Private Equity Case Study: Formats, Take-Home Process, and Recommendation
A private equity case study asks whether the fund should buy. Here is how take-home, timed Excel, and paper formats differ, what belongs in the model versus the memo, and how to present an invest-or-pass call.
A private equity case study asks one question: would the fund buy this company at this price? You get a packet (often a confidential information memorandum (CIM), a 10-K, or a short prompt), you build or sketch a leveraged buyout, and you defend an invest-or-pass call in a memo or a short slide deck.
Firms use three different artifacts under the same label. A paper LBO is a ten-minute mental-math drill. A timed LBO modeling test is a one-to-three-hour Excel speed check. A take-home case is a multi-day research and recommendation package. This page is about the take-home and the live discussion that follows it. The paper drill and the timed Excel build already have their own homes in the curriculum.
What a private equity case study is
In recruiting, "case study" means an investment decision under incomplete information. The interviewer is not grading whether you can recreate every line of a banker's model. They are grading whether you sound like someone who could sit in investment committee and say yes or no with a reason.
The packet varies. Some processes hand you a CIM and a few assumptions (entry multiple, leverage, hold). Some ask you to pick any public company that fits the firm's strategy and build the case from filings. Some compress the same work into a two-to-four-hour on-site session with a shorter deck. Growth-equity and operating-focused shops sometimes swap a full leveraged buyout (LBO) for a three-statement forecast or a commercial case on pricing and costs. The constant is the recommendation.
A finished case usually has three pieces:
- A simple LBO (or a light model the prompt allows) that produces Internal rate of return (IRR) and Multiple on invested capital (MOIC) under base, upside, and downside cases.
- A short memo or 8 to 15 slides that lead with the decision.
- A live Q&A where partners pressure the two or three assumptions that actually move returns.
If you only ship a long spreadsheet, you have not finished the case.
Which format you should expect
Format follows recruiting clock and fund size more than brand name.
Megafund on-cycle weekends in the United States compress dozens of candidates into a short window. There is no time for every applicant to research a company for a week. You should expect a paper LBO early and a timed Excel test in later rounds. The open-ended take-home is uncommon in that rush.
Middle-market, lower-middle-market, and many off-cycle processes reverse the weights. Headcount is smaller. Partners have time to read a memo. You are more likely to get two to seven days with a CIM or public filings, a model built from a blank sheet or a light template, and a presentation. That take-home is often the last filter before an offer.
Specialist strategies change the content, not the job of the case. Distressed and credit seats lean into capital structure and recovery. Growth equity leans into unit economics and path to profitability with less debt paydown. Sector funds expect you to speak the industry's operating metrics without being handed them.
Before you start Excel, read the prompt for three facts: the firm's strategy, the deliverable (model only, model plus memo, model plus slides), and any required assumptions. If those are missing in a live setting, ask. Clarifying the hurdle rate and the hold period is investor behavior, not a stall.
If the firm asks you to pick the company, match the mandate before you fall in love with a story. Prefer businesses with readable filings, enough detail to forecast drivers, and free cash flow that can service a normal buyout capital structure. Drop names that trade at software multiples when the brief describes a classic cash-flow buyout. Drop names with two-page cash flow statements you cannot clean in a day. The screen is part of the case, not a prelude you can rush.
Consulting PE cases vs PE firm case studies
Search results mix two different interviews. Consulting firms (McKinsey, BCG, Bain, and peers) give "private equity cases" that simulate commercial due diligence for a sponsor client. Those cases run 30 to 45 minutes, use a verbal framework, and rarely require an Excel LBO. The output is a spoken recommendation on market, company, and risks.
A case study inside a private equity recruiting process is different. It is graded as investment work product: sources and uses, debt paydown, returns, and a thesis the fund could own. If you prepare only consulting frameworks for a PE take-home, you will underbuild the model and overbuild the market sizing monologue. If you prepare only LBO mechanics for a consulting PE case, you will miss the diligence structure the interviewer expects.
When the firm is a buyout shop and the materials look like a CIM or a 10-K, use this page. When the firm is a consulting partnership and the case is a live conversation about whether a PE client should acquire, use a consulting case method instead.
How to work the case under the clock
Treat the clock as part of the test. A clean week-long take-home still collapses if you spend five days on Excel and one night on the story.
A workable split for a multi-day take-home:
- Day 1. Read the prompt and the firm's strategy. If you must pick the company, screen for strategy fit, data quality, and a valuation range where leverage still clears a sensible return. Do not pick a 30x EBITDA compounder for a classic buyout brief.
- Days 2 to 3. Learn how the company makes money. Identify two or three operating drivers (customers, price, volume, utilization, retention, same-store growth). Skim industry context only as far as it changes those drivers.
- Days 4 to 5. Build a simple LBO. Stop when sources and uses, free cash flow, debt schedule, returns, and two sensitivity tables work. A few hundred rows is enough.
- Final day. Write the recommendation. Let the sensitivities decide the wording. Rehearse a two-minute open that states invest or pass and the three reasons.
For a two-to-four-hour on-site case with a CIM, invert the order slightly: skim for business model and key numbers in the first twenty minutes, lock a simple model next, then spend the last third on slides and the verbal thesis. Forum write-ups of three-hour CIM cases keep repeating the same failure: model fine, business analysis thin.
Under time pressure, make labeled assumptions when data is missing. Tell the interviewer what you assumed. A transparent proxy beats a silent hole.
What belongs in the model
The model exists to support a decision. It is not the decision.
Minimum useful contents for a standard buyout take-home:
- Transaction assumptions: entry enterprise value or entry multiple, hold period, exit multiple cases, management equity if the prompt requires it.
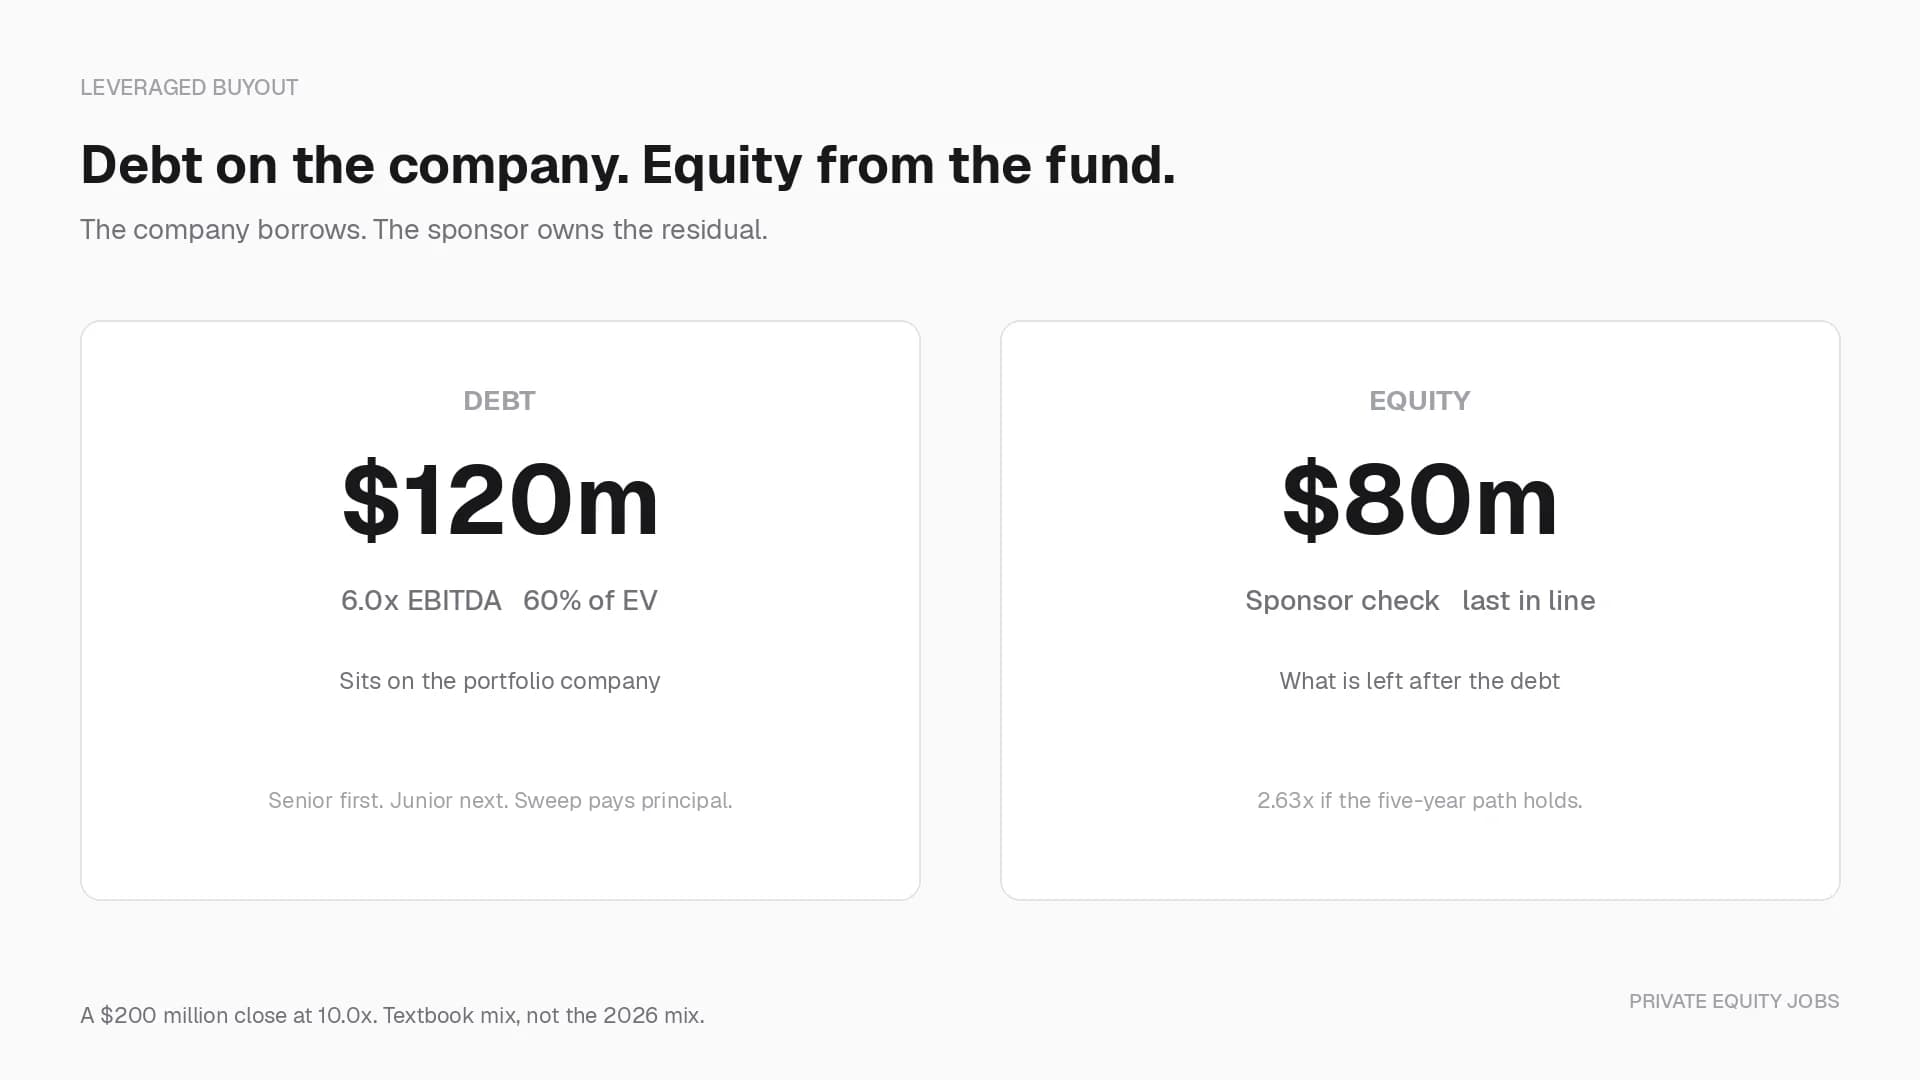
- Sources and uses that solve for sponsor equity.
- Operating forecast driven by the two or three drivers you named, not a single revenue growth rate pasted for five years without comment.
- Free cash flow that feeds debt paydown.
- A debt schedule simple enough to explain out loud (revolver and term loan is fine unless the prompt forces more).
- Returns: IRR and MOIC in base, upside, and downside.
- Sensitivities: entry versus exit multiple, and growth versus margin (or leverage versus exit).
Skip circular interest unless you have spare time. Skip a full three-statement build unless the prompt demands it. Skip ornate add-on modules if the thesis does not depend on them. Partners will not give extra credit for rows they cannot audit in a minute.
If the prompt is open-ended and the strategy is turnaround or buy-and-build, say so in the thesis and keep any add-on schedule crude but explicit. If the deal only works with heroic acquisitions, that is a finding, not a formatting problem. Tie value creation language to the live private equity value creation playbook: earnings growth, multiple, and leverage, with named initiatives rather than a slogan list.
Know what IRR versus MOIC emphasizes. A high IRR on a short hold can hide a weak absolute profit. A high MOIC on a long hold can miss the fund clock. State both.
How to write the recommendation
Lead with the answer. "I recommend the fund pursue this at 8.0x EBITDA for three reasons" or "I recommend passing at the asked price." Do not save the verdict for slide twelve.
A practical slide or memo spine:
- Decision and criteria. Invest or pass, target return, and the two or three conditions that must hold.
- Company and market. Business model, customers, and why this file fits the firm's strategy.
- Returns bridge. Entry equity, debt paydown, earnings growth, exit assumptions, IRR/MOIC range from the sensitivities.
- Value creation plan. Three to five specific initiatives with a mechanism and a timeline. "Improve margins" is not a plan. "Consolidate two plants into one within eighteen months, with a named cost line and a CapEx ask" is a plan.
- Risks and mitigants. The single risk that breaks the thesis first, then two secondary risks. Say what diligence would change your mind.
- Exit. Realistic buyer set (strategic, sponsor-to-sponsor, or IPO) and why the exit multiple is not a wish.
Write like an IC memo, not like a teaser. Short sentences. Numbers next to claims. If you are passing, say what price or structure would flip you. If you are investing, say what would make you walk.
A useful pattern for examples without inventing fake precision: strong cases name a fragmented market, contractible cash flows, and a bolt-on pipeline at lower multiples than entry. Weak cases stack three heroic assumptions (accelerating growth that contradicts the company's recent deceleration, margin expansion without a cost mechanism, and an exit multiple with no buyer set). Partners notice the stack.
Questions after you submit
The Q&A is where many offers die. Expect versions of these:
- Walk me through the thesis in sixty seconds.
- What is the single biggest risk, and why is it not fatal?
- Which assumption moves IRR the most, and by roughly how much?
- What would make you pass?
- Who buys this in year five?
- What would you ask management if you had an hour?
- Why this entry multiple rather than one turn higher?
Answer with a priority order. Equal-weight laundry lists of five risks signal that you have not chosen. If you do not know a fact, say how you would get it. Defensiveness reads worse than a clean gap.
Practice the open aloud. The first thirty seconds set whether the room treats you as an investor or as a model jockey. The rest of the private equity interview questions pack still applies: fit, deal discussion, and firm knowledge do not disappear because you submitted slides.
Mistakes that sink the case
Overbuilding the model. A 500-row file with no thesis loses to a shorter file with a clear decision. Finish returns and sensitivities before you decorate.
Hedging the recommendation. "It depends" without a stated decision is a fail. PE work is deciding with incomplete information. Conditional language belongs after the verdict ("invest if customer concentration below X is confirmed"), not instead of it.
Generic value creation. If the initiative could apply to any company in any industry, it is not diligence. Name the driver, the dollar or margin path, and the operational owner.
Ignoring downside. Show a case where you lose money or miss the hurdle, and say whether that outcome is acceptable. Capital preservation is part of the job.
Wrong artifact. Bringing a consulting framework to a PE take-home, or a full LBO to a consulting PE case, wastes the room's patience. Match the format section above.
Fighting the firm's strategy. A brilliant deep-tech growth story fails a classic industrial buyout prompt. Fit the mandate you were given.
How to practice
Reps matter more than another article.
- Build five to eight simple LBOs from public filings on a timer until sources and uses, debt, and returns are automatic. Use the LBO modeling test page for the timed Excel muscle.
- For take-home reps, pick companies in industries you already know. Open-ended research is slower when you are learning the sector and the case method at once.
- Keep a reusable slide skeleton (decision, company, returns, value creation, risks, exit). Reuse structure, rewrite content.
- Present to a peer who is allowed to interrupt. Record the first minute and cut filler.
- Read one real sponsor portfolio write-up or earnings transcript a week and practice stating the thesis and the fatal risk in two sentences.
You do not need twenty full take-homes. You need enough that the mechanics are boring and the judgment is awake.
When you are ready to apply, use the Private Equity Jobs board and the companies directory to target funds whose process matches the format you practiced.
Sources
Process and format distinctions across take-home, timed Excel, and paper LBO cases are drawn from opened recruiting guides on Mergers & Inquisitions (Private Equity Case Study), Growth Equity Interview Guide, Leland's case study guide, and IB Interview Questions' framework page, plus the consulting-versus-PE-firm contrast on Hacking the Case Interview's private equity case interview page. Forum cards on Wall Street Oasis and Reddit supplied practitioner order-of-work notes, not facts. No primary industry report figure was required for this process explainer.